Why Do Health Insurance Companies Deny Claims?
How Does a Health Insurance Claim Denial Happen?
Key Takeaway: A claim denial means the insurer adjudicated a submitted bill and refused to pay all or part of it. Your provider sent diagnosis codes, procedure codes, and your member ID. The payer compared that packet to plan rules and returned a denial with a reason code on your Explanation of Benefits.
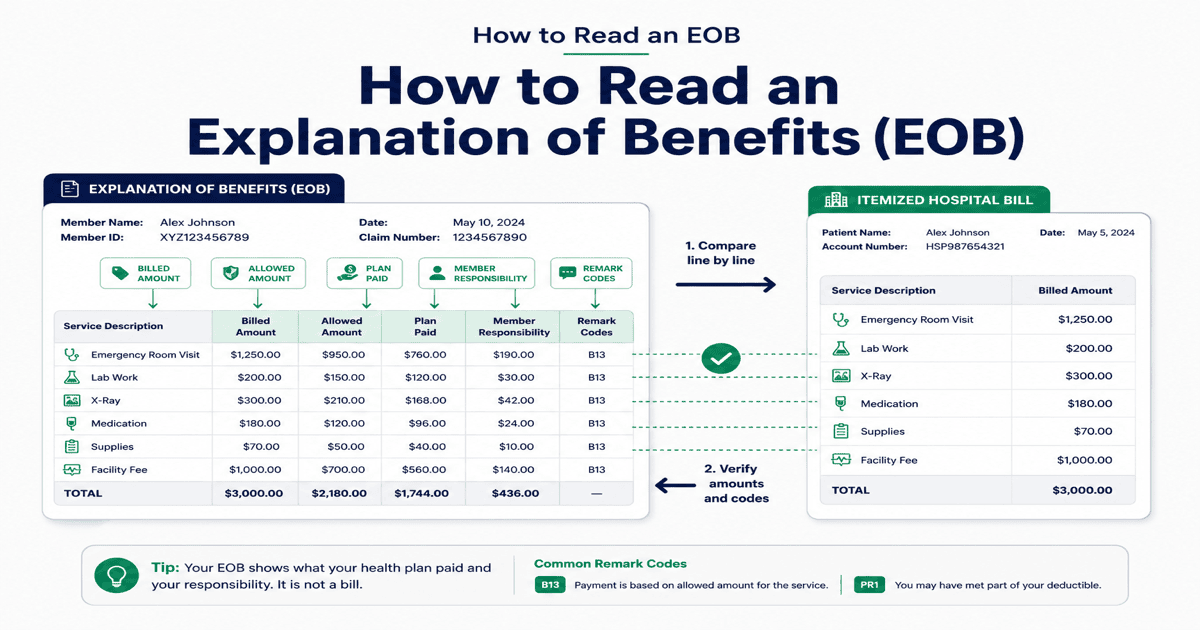
When patients ask why health insurance companies deny claims, they are usually looking at an Explanation of Benefits showing a charge the plan refused to pay. That decision applies to a specific claim on a specific date. It is different from asking whether a type of care is covered under your benefits package at all.
Claim Adjustment Reason Codes (CARC) such as CO-50, CO-197, and CO-16 appear on remittance advice and many EOBs. Remark codes add detail. Read the denial letter and EOB together. The code tells you which documentation or process failed, which also tells you what your appeal must fix. For whether a denial is legally allowed at all, see can insurance deny a claim.
What Are the Most Common Denial Reasons and CO Codes?
Key Takeaway: Most denials trace to a identifiable rule: authorization, medical necessity, network status, coding, pharmacy step therapy, plan exclusions, duplicates, or late filing. Match your code to the right response. A corrected claim fixes data errors. A member appeal addresses clinical or coverage disputes.
| Reason / code | What the insurer is saying | Appeal path |
|---|---|---|
| Prior authorization missing (CO-197) | Required pre-approval was not on file before the service | Internal appeal with auth request records, retroactive authorization, or urgency documentation. See how to appeal a prior authorization denial. |
| Medical necessity (CO-50) | Service does not meet the plan clinical or coverage criteria | Member appeal with physician letter, test results, and citations to the medical policy named on your denial. Request peer-to-peer review when your plan offers it. |
| Missing information (CO-16) | Claim lacks required fields or has billing errors | Ask your provider to submit a corrected claim first. Appeal only if corrected data is still denied. |
| Coding mismatch (CO-4, CO-11) | Diagnosis, modifier, or procedure codes do not align | Provider billing office reviews and resubmits corrected coding. Member appeal if the clinical record supports the billed codes. |
| Timely filing (CO-29) | Claim arrived after the payer filing deadline | Provider appeal with proof of original submission. Patient may appeal if the provider cannot resolve it and the plan allows member filing. |
| Out-of-network / non-covered (CO-45, CO-96, PR codes) | Provider is not contracted or benefit is excluded | Check emergency and facility-based protections under the No Surprises Act, then appeal with network inadequacy or medical necessity records when applicable. |
| Duplicate claim (CO-18) | Payer believes the same service was already paid | Compare EOBs and claim history. Appeal with proof the services were distinct or the prior payment applied to a different date of service. |
| Coverage ended (CO-27) | Service date falls after coverage terminated | Verify eligibility on the date of service. Appeal with enrollment records or COBRA continuation proof if coverage was active. |
| Step therapy / formulary | Required lower-cost drug trials were not documented | PBM formulary exception or step therapy override appeal with prescriber letter and pharmacy fill history. See how to appeal a step therapy denial. |
Codes can appear in combination. A CO-50 denial may sit beside remark codes that name the medical policy applied. Start with the primary CARC on your EOB, then read supporting remarks before you build your packet.
Why Do Insurers Use Prior Authorization and Medical Necessity Review?
Key Takeaway: Prior authorization and medical necessity review are utilization management tools in most plan contracts. They confirm services meet plan criteria before or after payment. A denial under these programs often means documentation was missing, not that your doctor chose the wrong treatment.
Health plans use prior authorization for high-cost services such as imaging, surgery, specialty drugs, and durable medical equipment. If authorization is missing, expired, or does not match the billed service, the claim can deny automatically even when the care was appropriate.
Medical necessity review compares your records to clinical guidelines or plan medical policies. Denials often cite InterQual, MCG, or proprietary criteria. Your appeal should map diagnosis codes, treatment history, and failed alternatives to the policy language on your denial letter. A generic physician note rarely answers the question the reviewer asked.
Common myth: Insurers deny claims at random to avoid paying. Most denials name a specific rule violation you can address with records, a corrected claim, or a formal appeal filed before your deadline.
How Are Pharmacy Denials Different From Medical Claim Denials?
Key Takeaway: Prescription denials route through your pharmacy benefit manager, not your medical carrier. Submitting a medical appeal for a denied prescription at the pharmacy counter will not reach the entity that adjudicated the claim.
Check the back of your insurance card. Your medical carrier and PBM may use different phone numbers and portals. Pharmacy rejections often reference step therapy, formulary exclusion, or quantity limits rather than medical CARC codes.
For a denied specialty drug, gather the rejection message from the pharmacist, your prescriber's letter, and pharmacy claims showing required trial drugs. File through the PBM appeal channel listed on your plan documents. For formulary disputes, see formulary exception denied: what to do.
Weak vs. Strong Appeal Language
Key Takeaway: Reviewers scan for the reason code, dates, and clinical support tied to plan policy. Vague frustration without records rarely changes a denial. Specific citations and attached evidence do.
| Weak statement | Strong statement |
|---|---|
| “I do not understand why my claim was denied. I have insurance.” | “I appeal denial CO-197 for claim dated 7/12/2026. Prior authorization reference PA-33821 was submitted before service. Attached: auth confirmation, clinical notes for ICD-10 M54.16, and treating provider letter.” |
| “My doctor ordered this test so it should be covered.” | “CO-50 denial for knee MRI. Attached: six weeks of conservative therapy, effusion documented on exam, and physician letter citing the plan medical policy section named on my denial notice.” |
| “Please reconsider. I pay my premiums every month.” | “Claim #CLM-2026-88104, denial dated 6/28/2026. I request the claim file and submit this Level 1 internal appeal with operative report and pathology results attached. Appeal deadline per notice: 12/25/2026.” |
Use AppealFlow'shealth insurance appeal letter generatorto draft a structured appeal letter tied to your denial reason before the deadline on your notice.
Need an Appeal Letter for a Denied Claim?
AppealFlow drafts regulation-informed appeal letters for health insurance denials. Edit live, then download as PDF or Word.
What Appeal Rights Apply After a Claim Denial?
Key Takeaway: Federal law requires most employer and marketplace plans to issue written denials with appeal instructions. ERISA governs many job-based plans. ACA Section 2719 governs internal and external review for many individual and small-group plans. Medicare and Medicaid use separate processes.
Under ERISA, employer-sponsored group health plans must follow claims procedure rules in 29 CFR 2560.503-1. Your adverse benefit determination must explain the reason, cite plan provisions, and tell you how to appeal. You can request the claim file the plan relied on.
ACA marketplace plans must offer internal appeals and, for qualifying cases, external review through an independent review organization under Healthcare.gov appeal rules. For deadline patterns by plan type, see how long you have to appeal a health insurance denial. A phone call to member services does not replace a written appeal through the portal or address on your notice.
What Should You Do When Your Claim Is Denied?
Key Takeaway: Read the reason code, confirm the appeal deadline, and choose between a corrected claim and a member appeal. Clinical denials need records that answer the insurer's stated rationale. Coding denials often start with your provider's billing office.
- Request the written denial letter and Explanation of Benefits with the reason code
- Circle the appeal deadline on your calendar the day the notice arrives
- Match your response to the code: corrected claim for CO-16 or CO-4, member appeal for CO-50 or CO-197
- Request your claim file if the denial cites records you have not seen
- Submit through the correct portal and keep confirmation or mailing proof
For a full step-by-step workflow, read what to do when an insurance claim is denied. If the plan upholds the denial, review external review rules in what is an external review in health insurance.
What Mistakes Keep Denied Claims From Getting Paid?
Key Takeaway: Resubmitting the same prior authorization request after a denial is not an appeal. A formal appeal letter with new clinical evidence triggers a higher-level review and different legal protections on most plans.
- Missing the appeal deadline. Extensions are rare. Use the date printed on your notice.
- Appealing to the wrong entity. Medical claims go to your carrier. Pharmacy claims go to your PBM.
- Generic provider letters. The letter must address the specific denial code on your EOB.
- Skipping a corrected claim when the code is administrative. CO-16 and many coding edits resolve faster with a provider resubmission.
- Stopping after one denial. Internal denial may still allow external review on ACA and many state-regulated plans when you meet the criteria on your notice.
Frequently Asked Questions
Common questions about why health insurance companies deny claims and how CO reason codes map to appeal paths.
Generate Your Free Health Insurance Appeal Letter
AppealFlow drafts formal appeal letters for denied health insurance claims. Edit live, download as PDF or Word, and submit through your plan portal. No account required.
- 100% Free
- No Signup
- PDF & Word Export
Disclaimer: This article is for educational purposes only and does not constitute medical or legal advice. AppealFlow is not an insurance company or law firm. Plan terms, appeal deadlines, and coverage rules vary. Review your denial notice and plan documents, and consult a licensed professional when appropriate. For emergencies, call 911. See our full disclaimer.